This article was first published in Electronics Weekly here.
Malaysia has been part of the global semiconductor industry for more than 50 years, mainly as a major base for outsourced semiconductor assembly and testing. This remains an important strength, but the country is now trying to build a broader role in the chip value chain.
The government’s National Semiconductor Strategy (NSS), launched in 2024, sets out plans to develop stronger capabilities in areas such as integrated circuit (IC) design, advanced packaging, semiconductor equipment and manufacturing support.
For international technology providers, manufacturers and investors, this creates opportunities to support Malaysia’s next stage of growth, provided they understand where the market is heading and how the local ecosystem works.
Malaysia is building on an established base
Malaysia’s electronics and electrical sectors are some of the country’s main economic pillars, and semiconductor activity is concentrated in long-established manufacturing clusters such as Penang, Kulim and Selangor. Over the years, these locations have built up engineering talent, supplier networks and a strong presence of multinational companies.
The country’s role in assembly and testing has given it undeniable scale and credibility but it struggled to capture the semiconductor industry’s higher-value activity. Malaysia is now trying to change this. The NSS aims to move the country towards the cutting edge by strengthening local companies, attracting higher value investment, developing talent and encouraging more design and technology-led activity. The strategy targets a massive expansion of the ecosystem by training 60,000 highly skilled local engineers and attracting more than $100 billion in design and manufacturing investments.
The timing is also favourable. Global chip companies are reassessing supply chains because of geopolitical tensions, rising demand and the need for greater resilience. This is not only a reaction to recent disruption. Supply chain resilience has become a long-term strategic priority for semiconductor companies, governments and major customers that need more secure access to chips. Malaysia is well placed to benefit from this shift because it already has manufacturing experience, infrastructure and an established international company base.
Opportunities are moving up the value chain
Advanced packaging is one of the clearest areas of opportunity. As chips become more complex, performance improvements increasingly depend on how different components are integrated. This is especially important in the AI era, where advanced packaging and chiplets are becoming critical to improving performance, reducing power use and managing cost.
Malaysia’s existing strengths in assembly and testing give it a solid foundation but advanced packaging requires more sophisticated equipment, materials, process knowledge, testing systems and automation tools. This creates openings for overseas firms that can help manufacturers upgrade their capabilities.
AI is also driving demand across the wider semiconductor ecosystem. Growth in AI applications is increasing the need for data centres, high performance computing infrastructure, power management components, sensors, memory, testing capacity and more efficient manufacturing processes. This broadens the opportunity for companies that support the semiconductor value chain, including firms providing equipment, materials, automation, thermal management and production optimisation.
IC design is another area to watch. The NSS aims to establish at least 10 local IC design and engineering companies with revenue targets between $21 million and $1 billion. This will take time, but it is already increasing interest in design services, electronic design automation tools, verification expertise and specialist training.
There are also opportunities in wafer fabrication support. Malaysia is not trying to become the next Taiwan or Korea, but its growing semiconductor base still needs cleanroom technologies, process chemicals, precision components, metrology systems, maintenance services and production efficiency tools.
Last but not least, automation and factory digitalisation are becoming more important. Semiconductor plants require high uptime, tight quality control and consistent output. As companies move into more advanced processes, demand is likely to rise for robotics, machine vision, sensors, smart factory systems and industrial artificial intelligence. The opportunity is not limited to large equipment suppliers as niche firms with specialist technologies can also find openings where they solve specific production problems.
The ecosystem is concentrated but diverse
Malaysia’s semiconductor ecosystem is concentrated in several key locations. Penang remains the country’s main semiconductor cluster and one of Southeast Asia’s most important electronics hubs. Kulim has become an important location for wafer fabrication and related investment, while Selangor has strengths in electronics, automation, logistics and engineering services.
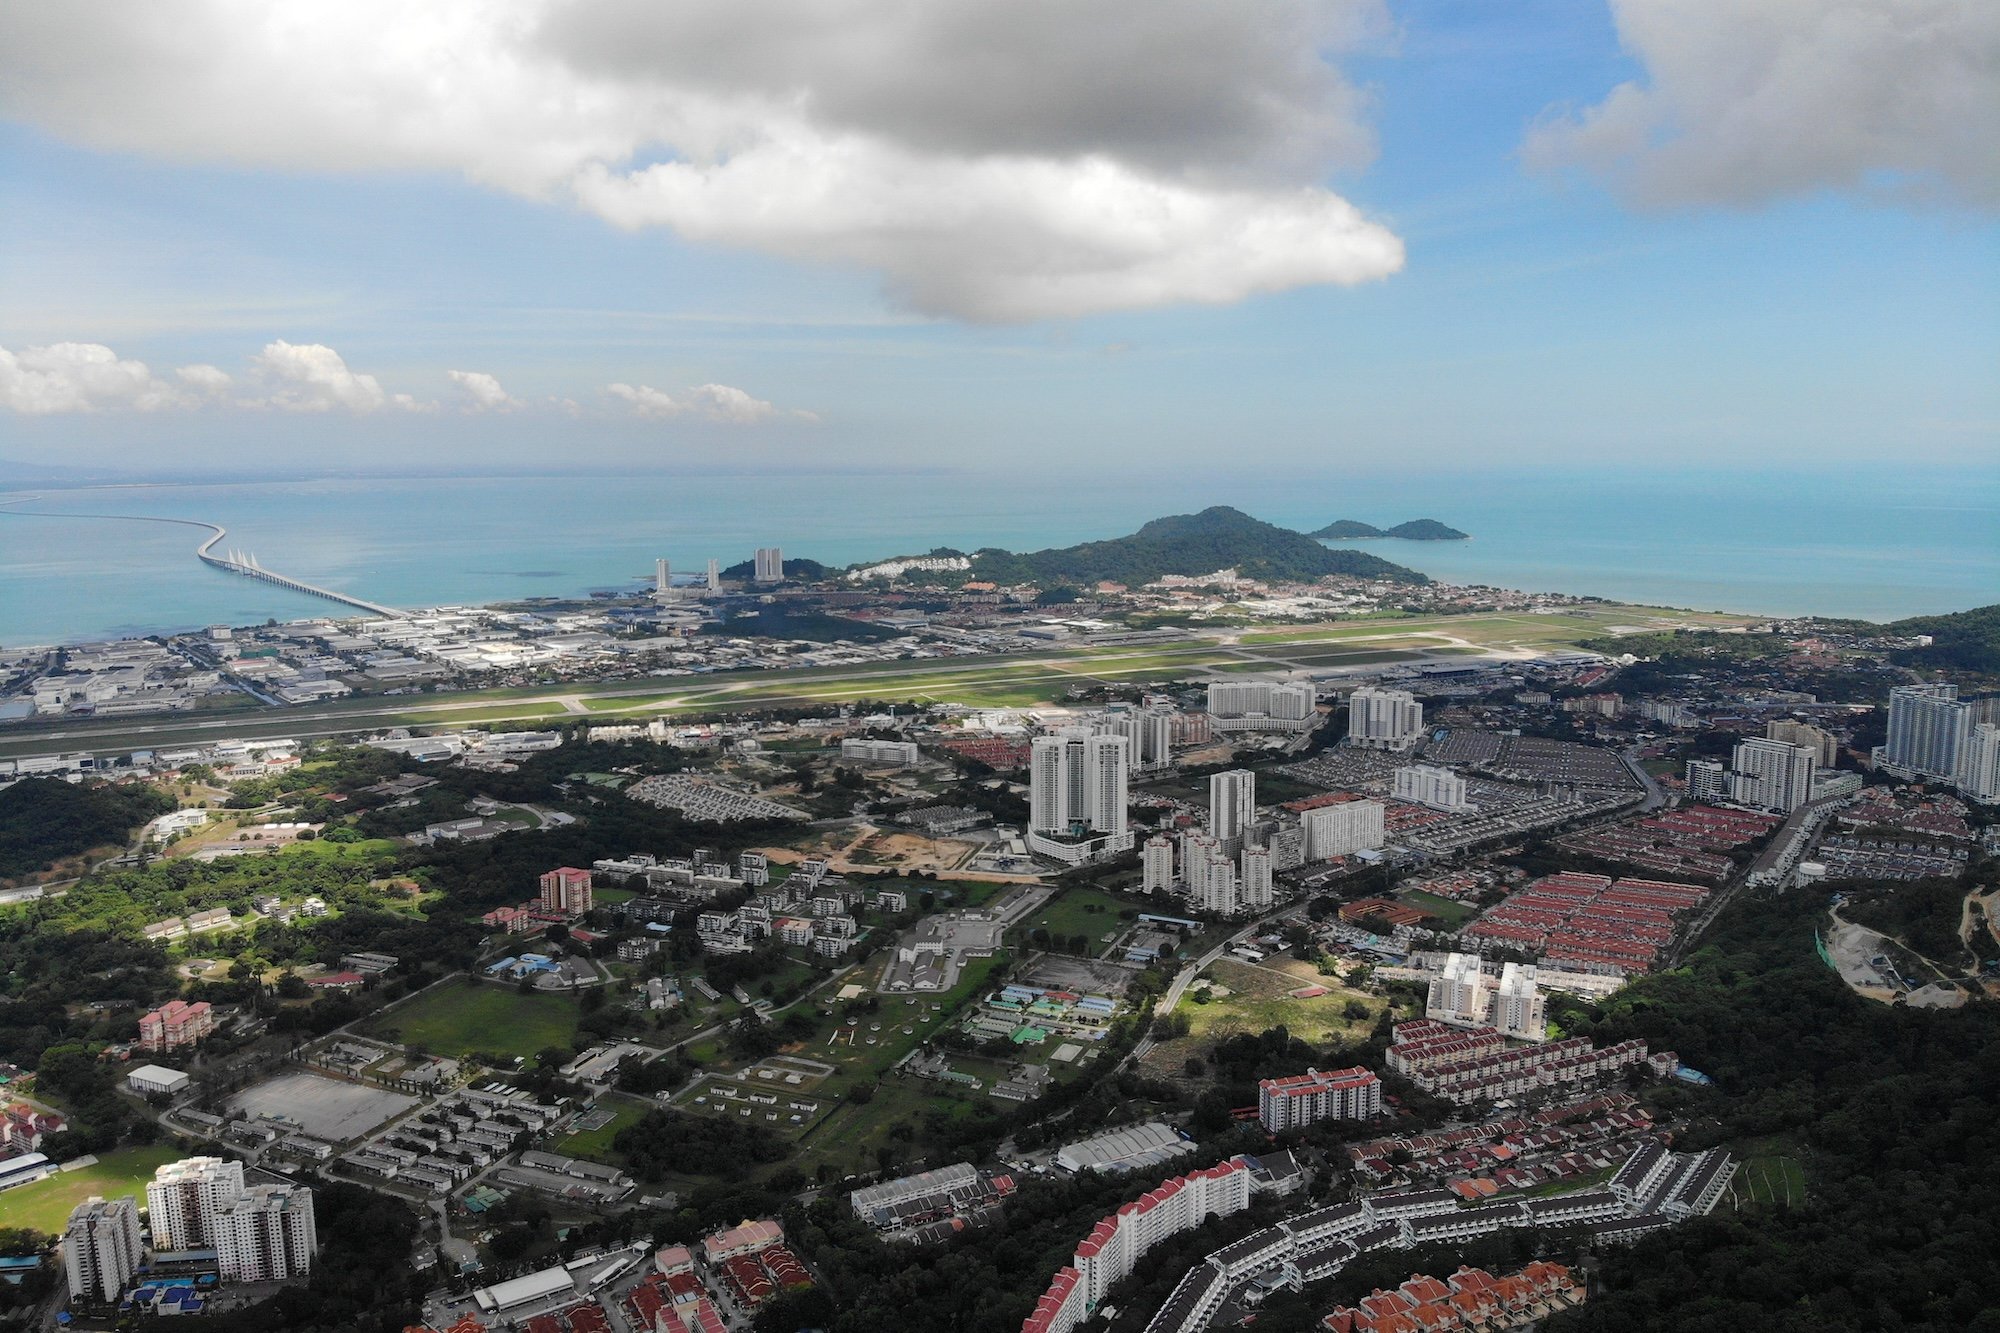
Bayan Lepan Industrial Park in Penang, home to global tech giants such as Intel, Dell, Bosch and AMD
These clusters are important because the future of semiconductors will not only depend on leading edge fabs. It will also rely on the strength of the wider ecosystem around them, including packaging, manufacturing support, engineering talent, suppliers and regional collaboration. This is where Malaysia has an opportunity to get ahead of the pack, especially as Southeast Asia becomes more important in global semiconductor supply chains.
There are two broad groups of industry players that overseas firms should understand. The first comprises multinational manufacturers including Intel, Infineon, ASE, Texas Instruments and Micron. These companies, which have significant operations in Malaysia and represent prime targets for overseas providers, usually have global procurement processes, high technical standards and clear priorities around productivity, quality and supply chain resilience.
The second group is made up of local suppliers and engineering companies. Many already support multinational manufacturers but some are now trying to move into higher value work themselves. These firms may become useful customers or partners, especially where they already have relationships with large manufacturers and understand local requirements and challenges.
Partnerships will be important
For international firms looking to grow their global footprint, the opportunity in Malaysia is practical: the market needs technologies and expertise that can help companies improve production, develop next-gen capabilities and strengthen the wider ecosystem.
Partnerships will often be the most effective route to market. Equipment, materials and automation firms may need to work with local distributors, system integrators or engineering service providers that already serve semiconductor customers in the region. Companies involved in design, research or training may find that universities, government-backed programmes and local technology firms are better entry points.
Overseas companies should also think carefully about customer type. Multinational manufacturers may offer larger opportunities, but qualification and procurement processes can take time. Local suppliers may be more accessible and faster moving but often need more support and may be more sensitive to cost. Government-backed initiatives can help open doors, but companies still need a clear value proposition and realistic expectations.
Talent development is becoming a constraint. Malaysia’s semiconductor ambitions will depend heavily on engineers, technicians and specialist managers, and shortages in these areas could slow progress if they are not addressed. Firms that can support training, knowledge transfer or applied research may be better positioned than those offering products alone.
A long-term market opportunity
Malaysia’s next challenge will be execution. Moving into cutting-edge semiconductor activities requires more than general enthusiasm and bold investment announcements. It will depend on whether the country can turn policy support, foreign investment and local capability building into a robust industrial base that companies can rely on over time.
This is where overseas firms need to be clear about their role in the market. Malaysia is not only a sales market but a place where companies can build relationships, support customers across the region and contribute to a more resilient semiconductor supply chain for decades to come. For some, that may mean investing in a local technical team or service presence. For others, it could be partnerships that develop gradually before larger opportunities follow.
The companies most likely to benefit will be those that enter early enough to understand the market as it develops, but carefully enough to avoid treating Malaysia as a simple alternative to existing semiconductor hubs. The opportunity is real, but it will reward firms that are patient, focused and useful to the ecosystem Malaysia is trying to build.
To discuss the potential of your semiconductor business in Malaysia, contact Amira at amira.azman@intralinkgroup.com
Amira Azman is our Country Manager for Malaysia. She has hands-on experience in Malaysia’s industrial and technology sectors including electronics, manufacturing and supply chains, and has helped overseas companies identify and connect with local partners for market entry and growth. She has authored in-depth studies involving stakeholder mapping, competitive analysis, supplier and distributor assessments and strategic recommendations across Malaysia’s manufacturing and innovation ecosystems. Amira holds a Master’s degree in ASEAN Studies from Universiti Malaya and a Bachelor’s degree in International Relations from the University of Queensland. She is fluent in English and Bahasa Malaysia.